


1. Introduction
The enactment of the Income-tax Act, 2025 represents a comprehensive structural overhaul of direct tax legislation in India, replacing six decades of incremental amendments under the Income-tax Act, 1961. The 2025 Act aims to eliminate obsolete provisions, streamline statutory drafting, and remove legal ambiguities that historically led to litigation.
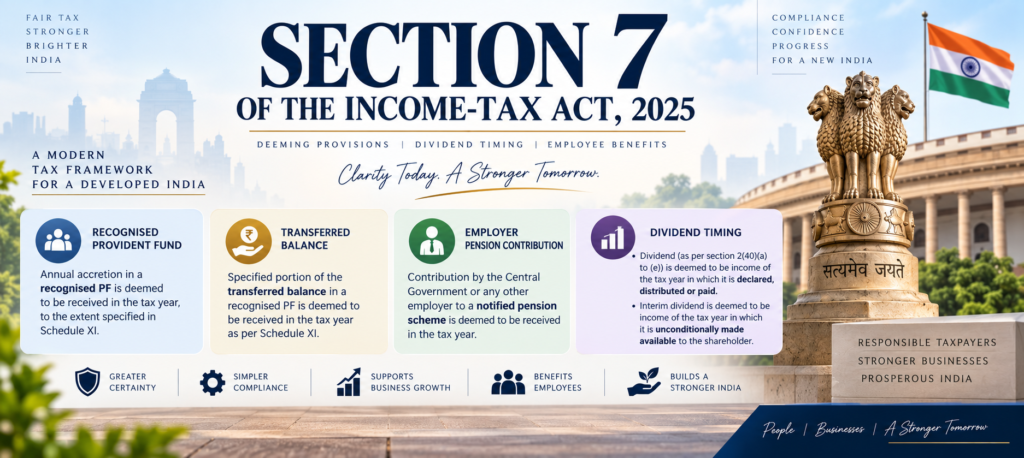
Section 7 of the Income-tax Act, 2025 serves as a core charging and deeming provision within the scheme of taxability for income earned from employment (“Income under the head ‘Salaries'”).
Under Indian income-tax law, income is generally taxed on an accrual or receipt basis, whichever occurs earlier. However, certain deferred benefits, accumulated employer contributions, and statutory funds do not strictly pass into the direct manual control of an employee during the year in which they are earned. Section 7 solves this legal dilemma by establishing specific statutory deeming fictions—statutorily deeming certain sums, contributions, and accredited balances as income received by the employee in the previous year, even if physical receipt occurs at a future date or upon retirement.
This guide provides a professional, clause-by-clause legal and practical analysis of Section 7 of the Income-tax Act, 2025 for tax practitioners, corporate finance leads, HR compliance teams, and taxpayers.
2. Statutory Text of Section 7
“Section 7. Income deemed to be received.
The following incomes shall be deemed to be received by the assessee in the previous year, namely:—
(i) the annual accretion in the previous year to the balance at the credit of an employee participating in a recognised provident fund, to the extent provided in sub-rule (1) of rule 6 of Part A of the Fourth Schedule;
(ii) the transferred balance in a recognised provident fund, to the extent provided in sub-rule (4) of rule 6 of Part A of the Fourth Schedule;
(iii) the contribution made, by the Central Government or any other employer in the previous year, to the account of an employee under a pension scheme referred to in section 80CCD.”
(Note: Where specific transitional rules apply under statutory schedules, references are interpreted alongside the corresponding procedural provisions of the Income-tax Rules.)
3. What Does Section 7 Mean?
Section 7 establishes the concept of “deemed receipt” for employment-related benefits.
1. What legal issue does it address?
Under general legal principles, a taxpayer cannot be taxed on money they have not physically or constructively received. If an employer deposits funds into a statutory provident fund or a government pension scheme, the employee often cannot withdraw those funds immediately due to lock-in periods. Without a specific deeming fiction, an employee could argue that such contributions are not taxable in the current year because they lack physical receipt. Section 7 explicitly creates a statutory legal fiction overriding this general principle.
2. Who is affected by Section 7?
- Salaried Employees: Individuals participating in a Recognised Provident Fund (RPF) or the National Pension System (NPS) / Unified Pension Scheme (UPS).
- Employers (Corporate, Government, and Private): Organizations responsible for computing correct Tax Deducted at Source (TDS) under employment income provisions.
- Trustees of Recognised Provident Funds: Entities responsible for calculating taxable interest and annual accretion elements.
3. Operational Mechanism & Tax Consequences
- Employer Contribution Over Limits: Employer contributions to a Recognised Provident Fund (RPF) exceeding the prescribed statutory limit (12% of salary) are deemed as income received by the employee during that previous year.
- Interest Accretions: Interest earned or accredited on an RPF balance exceeding the statutory rate cap is treated as deemed income.
- Employer Pension Contributions: Any contribution made by an employer (including the Central or State Government) to an employee’s NPS/pension account under Section 80CCD is deemed as income received in the year of deposit. It forms part of gross salary, subject to corresponding statutory deductions under chapter-specific provisions.
4. Key Terms and Definitions
To correctly interpret Section 7, several foundational terms must be understood as defined within the Act and its accompanying Schedules:
- Deemed to be received: A statutory legal fiction where the law mandates treating an amount as constructively received by the assessee in a specific previous year, regardless of actual physical possession or entitlement to immediate withdrawal.
- Annual Accretion: The total sum added to an employee’s provident fund account within a financial year, comprising employer contributions, employee contributions, and interest/yield accrued on the accumulated balance.
- Recognised Provident Fund (RPF): A provident fund recognized by the Chief Commissioner or Commissioner of Income-tax in accordance with the rules set out in the Schedules to the Act, or a provident fund established under a scheme framed under the Employees’ Provident Funds and Miscellaneous Provisions Act, 1952.
- Transferred Balance: The aggregate balance standing to the credit of an employee in an unrecognised provident fund at the date of its recognition, which is transferred to a recognised provident fund.
- Pension Scheme under Section 80CCD: The National Pension System (NPS) or any notified pension framework (such as the Unified Pension Scheme for government employees) governing contributions made by employers and individuals.
5. Conditions for Applicability
Section 7 applies when all the following conditions are satisfied:
1. Existence of Employer-Employee Relationship: The assessee must hold or have held an employment position where contributions are made by or on behalf of an employer.
2. Specific Fund/Scheme Involvement: The transaction must involve:
- A Recognised Provident Fund (RPF), OR
- An Unrecognised Provident Fund converting/transferring balances to an RPF, OR
- A Pension Scheme governed by Section 80CCD.
3. Exceeding Statutory Limits (for RPF):
- For annual accretion: The employer’s contribution exceeds 12% of the employee’s salary, or interest credited exceeds the rate notified by the Central Government (currently 9.5% per annum).
4. Actual Deposit/Credit in the Previous Year: The contribution or accretion must be credited to the employee’s account during the relevant previous year.
6. Detailed Clause-by-Clause Analysis
Clause (i): Annual Accretion to Recognised Provident Fund
- Scope: Covers excess annual contributions and excess interest credited to an RPF.
- Mechanism:
- Employer’s contribution up to 12% of salary (Salary = Basic Pay + Dearness Allowance if forming part of retirement benefits) is exempt. Any amount contributed by the employer in excess of 12% is deemed income under Section 7(i).
- Interest credited to the RPF up to 9.5% p.a. is exempt. Interest credited in excess of 9.5% p.a. is deemed income received under Section 7(i).
- Interplay with Monetary Caps: Under the overarching valuation framework, aggregate employer contributions across RPF, NPS, and approved superannuation funds exceeding ₹7,500,000 in a financial year, alongside annual interest/dividend accretions on such excess, are subject to tax as per the prescribed rules.
Clause (ii): Transferred Balance from Unrecognised to Recognised Fund
- Scope: Addresses situations where an Unrecognised Provident Fund (URPF) obtains formal recognition from the Income-tax Department.
- Mechanism: Upon recognition, the accumulated balance standing in the URPF is reassessed as if the fund had been recognized from its inception. The portion of the transferred balance representing past employer contributions and past interest thereon that would have been taxable had the fund been recognized in those past years is deemed income received under Section 7(ii) in the year of transfer/recognition.
Clause (iii): Employer Contributions to NPS/Pension Schemes
- Scope: Direct employer contributions to an employee’s account under Section 80CCD.
- Mechanism: Every rupee contributed by an employer (Central Government, State Government, PSU, or Private Entity) to an employee’s NPS account is deemed to be received by the employee in the year the contribution is made.
- Taxability Impact: The full employer contribution is first added to the employee’s Gross Salary under Section 7(iii). The employee then claims a deduction under Section 80CCD(2) up to prescribed limits (14% of salary for Central/State Government employees; 10% or 14% for private sector depending on the regulatory regime selected).
7. Sections to Be Read with Section 7
Section | Subject / Heading | Relationship with Section 7 | Why it is relevant | Practical impact |
Section 15 / 17 (2025 Act equivalent) | Chargeability of Salary & Perquisites | Direct cross-reference | Defines gross salary framework and perquisite valuations. | Section 7 deemed income gets added directly into gross salary computation. |
Section 80CCD | Deduction in respect of contribution to National Pension System | Direct cross-reference | Regulates the pension schemes referred to in Sec 7(iii). | Dictates the offsetting deduction available against Section 7(iii) deemed income. |
Fourth Schedule (Part A) | Rules relating to Recognised Provident Funds | Statutory mandate | Contains Rule 6 governing limits for excess contributions and interest. | Determines the exact quantitative excess deemed as income under Sec 7(i) & (ii). |
Section 192 | Deduction of Tax at Source (TDS) on Salaries | Compliance alignment | Mandates employers to compute TDS on all income components. | Employer must include Section 7 deemed receipts into monthly taxable salary for TDS. |
Section 10(11) / 10(12) equivalents | Statutory exemptions on Provident Fund payouts | Exemption alignment | Prescribes non-taxable limits for RPF accumulated balances. | Ensures non-exempt portions of accretions are correctly channeled into Section 7. |
8. Real-Life Illustrations
Illustration 1: Common / Straightforward Case (RPF Excess Contribution)
Facts: Mr. Rajesh earns a Basic Salary of ₹1,000,000 per annum (DA forming part of retirement benefits = Nil). His employer contributes 14% of Basic Salary (₹1,400,000) to a Recognised Provident Fund (RPF).
Relevant Provision: Section 7(i) read with Rule 6, Part A of Fourth Schedule.
Analysis: Exempt employer contribution limit = 12% of Salary = $12\% \times ₹10,000,000 = ₹1,200,000$. Excess contribution = $₹1,400,000 – ₹1,200,000 = ₹200,000$.
Tax Treatment: ₹200,000 is deemed as income received by Rajesh in the previous year under Section 7(i).
Conclusion: Included in gross salary under “Salaries” and taxed at applicable slab rates.
Illustration 2: Borderline Case (RPF Interest Accretion)
Facts: Ms. Anita has an RPF balance. For the financial year, the RPF trust credits interest at a rate of 10.5% per annum, amounting to ₹105,000 on her accumulated credit.
Relevant Provision: Section 7(i).
Analysis: Statutory maximum non-taxable interest rate = 9.5% p.a.
Exempt interest portion = $\frac{9.5}{10.5} \times ₹105,000 = ₹95,000$.
Excess interest = $₹105,000 – ₹95,000 = ₹10,000$.
Tax Treatment: ₹10,000 is deemed as income received under Section 7(i).
Conclusion: Added to taxable salary for the year.
Illustration 3: Case Where Provision Does Not Apply
Facts: ABC Ltd. contributes 10% of Basic Salary to an RPF for its employee, Mr. Vikram. The interest credited by the fund is 8.25% p.a.
Relevant Provision: Section 7(i).
Analysis: Employer contribution (10%) is within the 12% statutory cap. Interest rate (8.25%) is within the 9.5% statutory cap.
Tax Treatment: Nil deemed income under Section 7.
Conclusion: No addition to Vikram’s gross salary.
Illustration 4: Employer Example (NPS Contribution)
Facts: A private firm contributes ₹150,000 (10% of basic salary) to the NPS account of an executive under Section 80CCD.
Relevant Provision: Section 7(iii) read with Section 80CCD(2).
Analysis: Under Section 7(iii), the entire employer contribution of ₹150,000 is deemed to be income received by the executive.
Tax Treatment: Step 1: Add ₹150,000 to Gross Salary under Section 7(iii). Step 2: Claim deduction of ₹150,000 under Section 80CCD(2) in the tax computation.
Conclusion: Net taxable effect is neutral, but reporting on gross salary and claim of deduction is statutorily mandatory.
Illustration 5: Individual Taxpayer Example (Unrecognised Fund Recognition)
Facts: A company’s staff provident fund was unrecognised for 3 years. In Year 4, the fund obtains formal RPF recognition. The accumulated employer contribution plus interest standing to employee Suresh’s credit is ₹300,000.
Relevant Provision: Section 7(ii).
Analysis: The balance is recalculated under Part A of the Fourth Schedule as if the fund was recognized from day one. Assume ₹220,000 represents the statutory permitted limit and ₹80,000 represents excess employer contributions/interest over those 3 years.
Tax Treatment: The excess “Transferred Balance” of ₹80,000 is deemed as income received by Suresh in Year 4 under Section 7(ii).
Conclusion: Taxable as salary income in the year of conversion/recognition.
Illustration 6: Complex Corporate Example (Aggregated Cap Exceeded)
Facts: Ms. Priya, a senior corporate executive, receives a Basic Salary of ₹6,000,000. Her employer contributes:
RPF (12% of basic) = ₹720,000
NPS (10% of basic) = ₹600,000
Total Employer Contribution = ₹1,320,000.
Relevant Provision: Section 7(i) & 7(iii) read with aggregate perquisite rules.
Analysis:
Section 7(iii) includes ₹600,000 (NPS) in gross salary.
Section 7(i) evaluates RPF (₹720,000 is within 12%).
Aggregate Check: Total employer contribution across RPF + NPS = ₹1,320,000. The statutory aggregate non-taxable threshold is ₹750,000.
Excess aggregate contribution = $₹1,320,000 – ₹750,000 = ₹570,000$.
Tax Treatment: ₹570,000 is treated as a taxable perquisite/deemed receipt, alongside interest/annual accretion attributable to this excess.
Conclusion: The executive’s gross taxable income increases by ₹570,000 plus calculated dividend/interest accretions.
9. Detailed Worked Example
Fact Pattern
Employee: Mr. Anand (Senior Corporate Vice President)
Basic Salary + DA (retirements): ₹12,000,000
Employer RPF Contribution: 13% of Basic Salary = ₹1,560,000
Interest Credited to RPF Account: 10% p.a. on accumulated credit (total interest credited = ₹500,000)
Employer NPS Contribution: 10% of Basic Salary = ₹1,200,000
Step-by-Step Computation & Statutory Application
Step 1: Evaluation of Section 7(i) — RPF Excess Contribution
– Total Employer Contribution to RPF = ₹1,560,000
– Statutory Exempt Limit (12% of ₹12,000,000) = ₹1,440,000
– Deemed Income under Sec 7(i) [Excess Contribution] = ₹120,000
Step 2: Evaluation of Section 7(i) — RPF Excess Interest Credited
– Total Interest Credited at 10% p.a. = ₹500,000
– Statutory Exempt Limit at 9.5% p.a. (₹500,000 * 9.5 / 10) = ₹475,000
– Deemed Income under Sec 7(i) [Excess Interest] = ₹25,000
Step 3: Evaluation of Section 7(iii) — Employer NPS Contribution
– Total Employer Contribution to NPS = ₹1,200,000
– Deemed Income under Sec 7(iii) = ₹1,200,000
Step 4: Aggregate Employer Contribution Cap Verification (RPF + NPS + Superannuation)
– Aggregate Contributions Made (RPF ₹1,560,000 + NPS ₹1,200,000) = ₹2,760,000
– Overall Non-Taxable Monetary Cap = ₹750,000
– Excess Aggregate Employer Contribution = ₹2,010,000
*(Note: The higher excess evaluated under monetary perquisite rules takes precedence
to prevent double taxation of the same excess portion).*
Step 5: Final Taxable Salary Addition Calculation
– Base NPS Addition [Sec 7(iii)] = ₹1,200,000
– RPF Excess Contribution Addition [Sec 7(i)] = ₹120,000
– Excess RPF Interest Addition [Sec 7(i)] = ₹25,000
– Balance Perquisite on Aggregate Excess = Adjusted via Form 16
Final Conclusion: A total of ₹1,345,000 (under direct Sec 7 clauses) plus applicable perquisite adjustments on the aggregate threshold excess is included in Mr. Anand’s Gross Salary. Anand can claim an offsetting deduction under Section 80CCD(2) up to applicable limits against the ₹1,200,000 NPS component.
10. Case Law and Judicial Interpretation
Because the Income-tax Act, 2025 is structured to streamline direct tax law, judicial principles established under corresponding provisions of the Income-tax Act, 1961 remain highly persuasive where statutory wording remains materially identical.
Case / Citation | Court | Year | Key Issue | Principle Established | Relevance to Section 7 |
CIT v. L. W. Russell (1964) 53 ITR 91 | Supreme Court | 1964 | Vested interest vs. contingent interest in employer contributions. | Contributions made by an employer toward an employee benefit scheme are taxable only when the employee acquires a vested, non-contingent interest. | Underpins the necessity of explicit statutory deeming fictions in Section 7 to tax contributions regardless of delayed vesting. |
Morvi Industries Ltd. v. CIT (1971) 82 ITR 835 | Supreme Court | 1971 | Direct receipt vs. statutory deemed receipt. | Income accrues or is received based on statutory mandate, which can override contractual terms. | Affirms that statutory deeming under provisions like Section 7 operates automatically by law, irrespective of private agreement terms. |
Express Newspapers Ltd. v. CIT (1997) 227 ITR 59 | Madras High Court | 1997 | Taxability of transferred balances upon recognition. | Transferred balance calculations must strictly follow the statutory rules of the Fourth Schedule without arbitrary additions. | Protects taxpayers from over-assessment under Section 7(ii) during fund recognition transitions. |
Statutory Position: No substantive appellate rulings exist interpreting Section 7 of the 2025 Act specifically, given its recent enactment. However, jurisprudence under Section 7 of the 1961 Act applies directly due to continuity in legislative intent.
11. Relevant Rules, Notifications and CBDT Guidance
The operation of Section 7 relies directly on secondary legislation and administrative guidelines:
1. Fourth Schedule to the Income-tax Act (Part A):
- Rule 6(1): Sets the 12% employer contribution threshold and 9.5% interest rate cap for annual accretions under Section 7(i).
- Rule 6(4): Outlines the exact formula for computing the taxable portion of “Transferred Balances” under Section 7(ii).
2. Income-tax Rules (Rule 3B equivalent):
- Specifies the computational formula for calculating taxable annual accretion (interest/dividend) on employer contributions exceeding ₹750,000 across RPF, NPS, and Superannuation.
3. CBDT Circular No. 709:
- Clarified employer obligations regarding TDS deduction on deemed salary items and employer NPS matchings.
12. Comparison with the Income-tax Act, 1961
Issue | Income-tax Act, 1961 (Section 7) | Income-tax Act, 2025 (Section 7) | Practical Significance |
Annual Accretion to RPF | Covered under Section 7(i). | Covered under Section 7(i). | Substantive Continuity: Retains identical limits (12% salary / 9.5% interest). |
Transferred Balance | Covered under Section 7(ii). | Covered under Section 7(ii). | Substantive Continuity: Statutory recalculation rules preserved upon fund recognition. |
NPS Contributions | Covered under Section 7(iii) (inserted post-2004). | Covered under Section 7(iii). | Structural Streamlining: Consolidated cleanly within the core deeming section. |
Drafting Architecture | Contained archaic language and redundant cross-references built up over 60 years. | Plain-language re-drafting with direct schedule references. | Clarity: Reduced ambiguity for automated payroll and TDS tax engines. |
13. Common Mistakes
1. Omitting NPS Employer Contribution from Gross Salary:
- Error: Taxpayers often exclude the employer’s NPS contribution from “Gross Salary” on the grounds that it is a direct employer deposit into a locked pension account.
- Correction: Section 7(iii) mandates that this sum must be added to Gross Salary first, after which an offsetting deduction is claimed under Section 80CCD(2).
2. Incorrect Definition of “Salary” for RPF 12% Cap:
- Error: Computing 12% of Gross Total Salary or Basic + Bonus.
- Correction: “Salary” for RPF calculation is strictly defined as Basic Salary + Dearness Allowance (if forming part of retirement benefits). Exclude bonuses, allowances, and perquisites.
3. Double Counting Excess Aggregate Contributions:
- Error: Taxing the 12% RPF excess under Section 7(i) and again adding the same excess under the ₹750,000 aggregate cap perquisite rules.
- Correction: Ensure computational adjustments prevent double taxation of identical underlying sums.
4. Ignoring Excess Interest Accruals:
- Error: Assuming interest credited by an RPF is completely tax-exempt regardless of the rate.
- Correction: Interest credited above 9.5% p.a. is deemed income under Section 7(i).
14. Practical Compliance Checklist
Tax professionals and payroll administrators can use this checklist to verify compliance under Section 7:
- Step 1: Has the employer made contributions to an RPF during the financial year?
- Step 2: If yes, does the contribution exceed 12% of (Basic + DA forming part) for any employee? If yes, classify the excess under Section 7(i).
- Step 3: Has the RPF credited interest exceeding 9.5% p.a.? If yes, calculate the excess interest and treat it as deemed income under Section 7(i).
- Step 4: Has an Unrecognised Provident Fund been converted/recognized during the year? If yes, obtain the calculation sheet under Rule 6(4) of Part A of the Fourth Schedule for Section 7(ii).
- Step 5: Did the employer contribute to an NPS account under Section 80CCD? If yes, include 100% of the employer’s contribution in Gross Salary under Section 7(iii).
- Step 6: Check aggregate employer contributions across RPF, NPS, and Superannuation against the ₹750,000 overall threshold.
- Step 7: Ensure all Section 7 deemed income figures are reflected in Form 16 (Part B) and reported accurately in the employee’s Income Tax Return (ITR).
15. Important Legal Nuances
A. Statutory Fiction Boundaries
A statutory deeming fiction must be strictly interpreted within the boundaries set by Parliament. Section 7 deems certain sums as “received in the previous year.” It cannot be extended beyond its statutory language to tax non-statutory or non-notified funds unless explicit rules apply.
B. Timing of Deemed Receipt
The timing of deemed receipt under Section 7 is explicitly linked to the date of credit/deposit in the previous year, not the date of ultimate withdrawal or retirement. This ensures tax liability aligns with the financial year of accrual/contribution.
C. Interplay between Section 7(iii) and Section 80CCD(2)
While Section 7(iii) deems the employer’s NPS contribution as income received, the actual tax burden depends on Section 80CCD(2). If an employer contributes 14% for a Central Government employee, the entire 14% is deemed income under Section 7(iii) and fully deductible under Section 80CCD(2). However, for a private sector employee where the deduction cap under specific tax regimes may be 10%, any excess contribution above 10% remains in net taxable salary.
16. Key Takeaways
- Section 7 creates statutory legal fictions that deem specified employer contributions and interest accretions as “income received” by the employee in the current year.
- Three primary triggers:
- RPF employer contributions of salary or interest credited p.a.
- Transferred taxable balances from unrecognised funds upon gaining recognition.
- Employer contributions to NPS/Section 80CCD pension schemes.
- Employer NPS deposits must always be added to gross salary under Section 7(iii) before claiming deductions under Section 80CCD(2).
- Payroll processing engines must dynamically track these statutory thresholds to avoid incorrect TDS withholdings under Section 192.
17. References and Official Sources
- Income Tax Department, Government of India (Official Portal): https://www.incometax.gov.in/
- Ministry of Finance, Government of India: https://www.finmin.gov.in/
- India Code (National Digital Repository of Acts): https://www.indiacode.nic.in/
- Central Board of Direct Taxes (CBDT) Circulars & Notifications: https://incometaxindia.gov.in/Pages/communications/circulars.aspx
Frequently Asked Questions (FAQs)
1. What does “income deemed to be received” under Section 7 actually mean?
It is a statutory legal fiction. Even if an employee does not physically receive cash or have direct access to funds in a given year (e.g., money deposited into a locked retirement account), the law deems that money to be received in that financial year for tax calculation purposes.
2. Is the employer’s contribution to my Provident Fund (RPF) fully taxable under Section 7?
No. Employer contributions to a Recognised Provident Fund (RPF) are exempt up to 12% of your salary (Basic Pay + DA forming part of retirement benefits). Any contribution by the employer exceeding 12% is deemed as income received under Section 7(i) and added to your gross taxable salary.
3. How is interest earned on my Provident Fund balance taxed under Section 7?
Interest credited to an RPF account is exempt up to a rate of 9.5% per annum. Any interest credited above 9.5% p.a. is treated as deemed income received under Section 7(i).
4. Why is my employer’s NPS contribution added to my gross salary if I cannot withdraw it?
Under Section 7(iii), 100% of the employer’s contribution to an employee’s pension account under Section 80CCD is deemed to be income received in the year of deposit. It is added to your Gross Salary first, and you then claim a corresponding deduction under Section 80CCD(2) on your tax return.
5. What happens if an Unrecognised Provident Fund (URPF) becomes a Recognised Provident Fund (RPF)?
The balance standing in the URPF is reassessed under Section 7(ii). The past employer contributions and past interest that would have been taxable had the fund been recognized in those prior years are aggregated and deemed as income received in the specific year the fund gains formal recognition.
6. Does Section 7 apply to my own (employee) contribution to the Provident Fund?
No. Section 7 governs employer contributions and interest/yield accretions. Employee contributions are part of the employee’s net take-home salary that has already been earned, and they are dealt with under deduction provisions (like Section 80C equivalents).
7. What is the definition of “Salary” when calculating the 12% RPF exemption limit?
For Section 7(i) calculations, “Salary” includes Basic Pay + Dearness Allowance (DA) (if DA forms part of employment retirement benefits). It excludes commissions (unless fixed percentage of turnover), bonuses, perquisites, and other allowances.
8. How does Section 7 interact with the ₹7,500,000 aggregate annual threshold for corporate benefits?
If the total employer contributions across RPF, NPS, and Approved Superannuation Funds exceed ₹7,500,000 in a financial year, the excess over ₹7,500,000—along with annual interest/dividend accretions attributable to that excess—is taxed as a perquisite. Section 7 covers the base deemed receipt, while perquisite valuation rules handle the excess interest accretion.
9. Does Section 7 apply to non-residents (NRIs) working for Indian companies?
Yes, if the employment services are rendered in India or paid by an Indian employer where statutory contributions are deposited in India. Deemed receipts under Section 7 form part of salary income sourced in India.
10. How does Section 7 affect Form 16 and monthly TDS deductions by my employer?
Employers are statutorily required under Section 192 (TDS on Salaries) to include all Section 7 deemed receipts (excess RPF contributions, excess interest, and full employer NPS match) in the monthly tax estimation matrix. These amounts appear under “Gross Salary” in Part B of Form 16.
11. Are dividends treated as “deemed income” under Section 7?
Under the Income-tax Act, 2025, Section 7 consolidated deemed receipts, including statutory provisions where declared or distributed dividends (and unconditional interim dividends) are deemed to be the income of the tax year in which they are declared or made available.
12. If my employer defaults or pays PF contributions late, does Section 7 still apply in that year?
Section 7 applies to the actual annual accretion credited or contributions made during the previous year. If an employer fails to deposit the funds into the RPF/NPS trust within the financial year, the deemed receipt trigger is deferred until the financial year in which the actual credit/deposit occurs.
Disclaimer
This article is intended for educational and informational purposes and should not be treated as legal or tax advice. Readers should verify the law and obtain professional advice based on their specific facts and circumstances.